You Shouldn't Have to Fight Your Insurance Company Alone
Summit Shield Roofing has handled hundreds of insurance claims across the Jackson metro. We know what adjusters look for and how to document damage thoroughly so the full scope of what's wrong is clear.
Want to understand how the claims process works before you call? Read our roof insurance claim guide.
The Process
Our Step-by-Step Insurance Claims Process
We handle the documentation and the roofing work — from inspection to final installation.
Free Storm Damage Inspection
We come out immediately to assess your roof. We photograph and document every piece of damage — hail dents, wind uplift, granule loss, and more. This documentation is critical for your claim.
Claim Filing Support
We help you understand what documentation and photos adjusters typically need, and we can guide you through filing your claim with your insurance company.
We Meet Your Adjuster
We show up at the adjuster appointment with you. We point out every piece of damage and ensure nothing gets missed. Our presence helps ensure the full scope of damage is documented.
Scope & Documentation
If the adjuster's scope is incomplete, we prepare a detailed supplement with additional photos and evidence to communicate the full scope of damage.
New Roof Installed
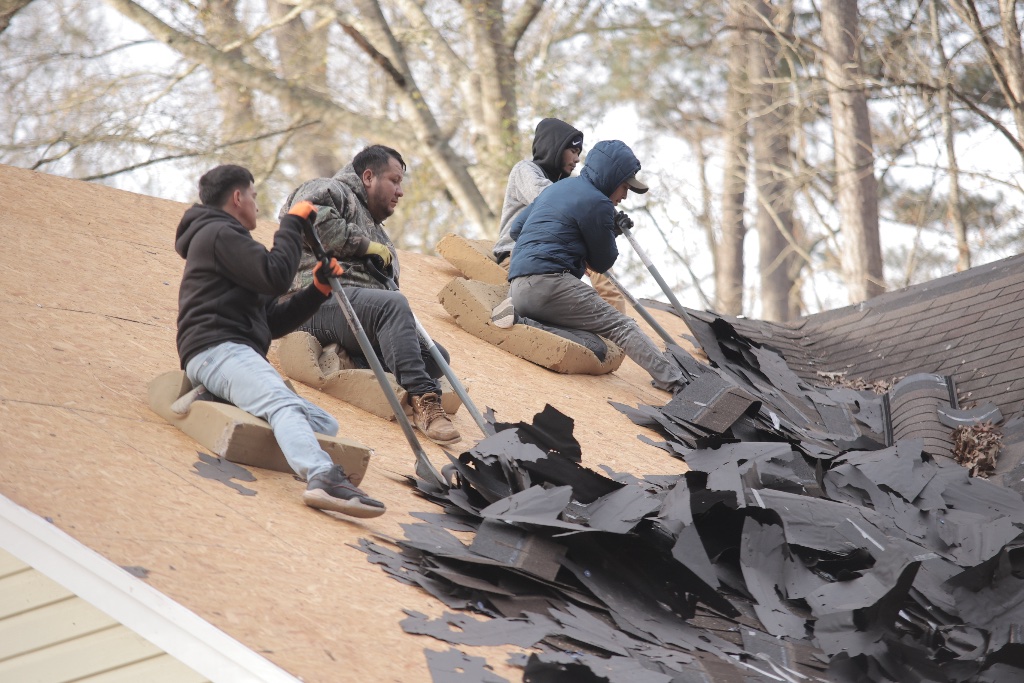
Once your claim is approved, we schedule installation. We handle permits, materials, crew, and cleanup.
Final Inspection & Warranty
We conduct a thorough final walkthrough with you, provide all warranty documentation, and follow up to ensure your complete satisfaction.
Adjuster Partnership
We Work Directly With Your Insurance Adjuster
Most homeowners make the mistake of meeting with an adjuster alone. Our experienced team knows how to professionally document and present every item of damage so nothing gets missed during the adjustment.
Complete Documentation
Professional photos of every damaged area, close-ups of hail impacts, granule loss measurements.
Scope Writing
We prepare detailed damage reports using industry-standard software (Xactimate).
Supplement Support
If the adjuster misses anything, we prepare supplements with additional photos and evidence.
No Pressure
We give you honest guidance. If your roof isn't eligible for a claim, we'll tell you.
Important: Act Within Your Policy Window
Most insurance policies require you to file storm damage claims within 1-2 years of the event. After severe weather, don't wait. Call us for a free inspection to see if you have a claimable loss.
Common Claimable Damage in Mississippi:
- • Hail damage from severe thunderstorms
- • Wind uplift and missing shingles
- • Tornado and straight-line wind damage
- • Tree limb and debris impact
Documentation
Documenting Roof Damage for Your Insurance Claim
A roof insurance claim lives or dies on documentation. The adjuster needs to see exactly what the storm did — where the damage is, how bad it is, and that it's storm-related and not pre-existing wear. That's why we photograph everything during the inspection, not just the obvious damage.
We document wind damage (lifted, creased, and missing shingles), hail damage (dents, granule loss, cracked mats), impact damage (tree limbs and debris), and any water entry in the attic. You get those photos. If you file a claim, they support what you're claiming. If the adjuster's scope is incomplete, we use them to prepare a supplement.
Not sure if your damage is storm-related? See our storm roof damage guide for what to look for.
What we document
Questions & Answers
Roof Insurance Claim FAQ
Real questions from homeowners across Flowood, Jackson, and Central Mississippi.
How does a roof insurance claim work?
It starts with a storm damage inspection — we get on the roof, photograph everything, and document the full scope of damage. You then file a claim with your insurance company, and an adjuster is assigned to inspect the roof. We meet the adjuster on-site, walk them through what we found, and make sure nothing gets missed. If the adjuster's scope is incomplete, we prepare a supplement with additional photos and evidence. Once the claim is approved and funded, we schedule the repair or replacement. The decision to file and the final outcome are between you and your insurance company — our role is to make sure the damage is thoroughly documented and clearly presented.
Should I file an insurance claim for roof damage?
It depends on the extent of the damage, your deductible, and your policy terms. If the repair cost is below your deductible, a claim may not make sense. If the damage is extensive — widespread hail, significant wind damage, or a large impacted area — a claim may be worth pursuing. We recommend having the roof inspected first so you know what's actually wrong and what the repair looks like before you decide. We can't tell you whether to file, but we can give you the information you need to make that decision.
What does an adjuster look for during a roof inspection?
An adjuster looks for documented evidence of damage — hail dents, wind-lifted or creased shingles, missing shingles, granule loss, damaged flashing, and any impact points. They'll also check the overall condition and age of the roof. Our job at the adjuster meeting is to point out every piece of damage we found during our inspection, make sure it's photographed and documented, and answer any questions about scope. We're there as your roofing contractor, not as your adjuster — we make sure the damage is clearly presented, but the coverage decision is your insurance company's.
What if the insurance adjuster missed damage?
It happens — adjusters inspect many roofs and sometimes miss items, especially damage that's subtle or in hard-to-reach areas. If we find that the adjuster's scope is incomplete, we prepare a supplement — a detailed document with additional photos and evidence that communicates the full scope of damage. This goes to your insurance company for review. We can't guarantee a supplement will be approved, but we make sure nothing we found is left out of the record.
Can Summit Shield help with a roof insurance claim if I already filed?
Yes. If you've already filed a claim and the adjuster has already inspected, we can still review the adjuster's report, compare it to what we find on the roof, and prepare a supplement if damage was missed. If the claim was denied and you believe damage exists, we can inspect and document what we find — though we can't promise a denied claim will be reopened or overturned, since that decision is your insurance company's.
Is Summit Shield a public adjuster or an insurance company?
No. Summit Shield is a licensed roofing contractor. We are not a public adjuster, an insurance company, or a law firm, and we don't provide legal advice. What we do is inspect your roof, document the damage thoroughly with photos, meet your adjuster on-site to walk through what we found, and prepare supplements if the initial scope is incomplete. The decision to file a claim, the coverage determination, and the final settlement are all between you and your insurance company. Our role is to make sure the damage on your roof is clearly and accurately documented.
Success Stories
Real Homeowners. Real Insurance Claim Stories.
"We had storm damage and I knew it but I dreaded going through the insurance process but Wyatt handled all that and then some. Highly recommended two thumbs up!"
Jamie Kincade
Flowood, MS
"Great customer service, and excellent work. Mr. Wyatt made sure that all the details of the work are taken care of in the best way. He is very accessible, always available to answer any questions and tireless effort with the insurance company following up on the claim. Highly recommend."
Ashraf A
Madison, MS
No Stress. No Hassle.
Let Us Help With Your Roofing Insurance Claim
Summit Shield Roofing has helped Flowood, Jackson, and Madison homeowners navigate the claims process. We know the documentation, and we know how to present it clearly.
Start Your Insurance Claim Today
Fill out our quick form and Summit will contact you to schedule your appointment.
Free inspection. No obligation. Serving Flowood, Jackson, and all surrounding areas.
Or call: (601) 414-9824